Search

In classical economics’ clockwork, idealized models, supply and demand unfailingly converge toward perfect equilibrium guided by the invisible hand of the price mechanism. In the nineteenth century, French economist Jean-Baptiste Say formulated a proposition that dominated economic doctrine for over a century: Say’s Law.
Put simply, the law states that “supply creates its own demand.” Its underlying logic is airtight: when an entrepreneur sets out to produce goods, they must procure raw materials, lease plant facilities, and—most crucially—pay wages to laborers. Flush with disposable income, those workers return to the market as consumers. Thus, so long as production continues, the gears of wealth turnover remain perpetual, rendering generalized, absolute overproduction impossible.
For two centuries, through every disruptive wave of industrial transformation, the ghost of Say’s Law stood vigil over capitalism’s structural foundation. Yet, as Silicon Valley’s AI capitalists hubristically attempt to excise the “worker wage” factor entirely from humanity’s productive equation, the centuries-old mechanism has ground to a screeching, violent halt.
What lies ahead is decidedly not the boundless growth and post-scarcity AI utopia showcased in keynote presentations. Instead, we are spiraling into a systemic abyss that threatens to drag both the real economy and the multi-trillion-dollar compute narrative down with it.
Silicon Valley’s Hubris and the Physical Limits of Marginal Propensity to Consume
Big Tech boardrooms and elite Wall Street strategists operate under an arrogant statistical illusion: that as long as corporate balance sheets expand exponentially and national GDP ticks upward, macroeconomic vitality will endure. Their spreadsheets project that even if aggregate wealth pools within a narrow oligarchy monopolizing compute infrastructure, these ultra-wealthy few can underwrite the macroeconomy through massive capital expenditures and exorbitant private consumption.
Yet these engineers and actuaries have blindsided themselves to an immutable axiom of macroeconomic reality: the diminishing marginal propensity to consume.
Human consumption capacity possesses absolute physical and biological limits.
Consider the reality of the broader populace. When a middle-class household sees its annual income jump from $50,000 to $100,000 via a promotion, almost every incremental dollar pours directly back into the real economy. They replace a decade-old sedan with a new SUV, book a family vacation to Japan, frequent upscale retail corridors, and dine out at higher-end establishments. Those discretionary funds function as a direct liquidity injection into the economic bloodstream, supporting automotive line workers, tour operators, retail clerks, and hospitality staff.
When wealth flows invert and aggregate intensely at the extreme right tail of an M-shaped distribution—into the hands of tech oligarchs and asset managers—this economic law turns merciless.
Suppose Mark Zuckerberg of Meta or Jensen Huang of Nvidia sees their net worth increase by an additional $1 billion this year. What real-economy multiplier effect does that windfall produce? Effectively zero. No individual, regardless of net worth, requires 100,000 iPhones, eats 1,000 fast-food meals a day, or maintains 10,000 streaming subscriptions. The overwhelming bulk of that capital never materializes as essential aggregate demand. Instead, it sits as idle ledger entries circulating within the financial apparatus, chasing yield and inflating asset bubbles across equities and prime real estate.
This exposes the most perilous, deliberately obscured blind spot of the AI boom: the enterprise clients funding Microsoft, Google, and AWS—the multinational retailers, automakers, and logistics conglomerates deploying multi-million-dollar AI suites—rely entirely on the purchasing power of everyday consumers to sustain their top line.
When enterprise clients slash white-collar headcount to salvage immediate margins, siphoning payroll from the middle class directly onto the balance sheets of a handful of compute providers, the foundation of aggregate consumption collapses. The spending power of Silicon Valley’s billionaire class can never close the catastrophic demand shortfall left behind by a gutted middle class.
The Domino Effect: From Real-Economy Stagnation to the Compute Collapse
The structural backlash triggered by collapsing aggregate demand will not hit like an instantaneous asteroid strike. It will spread like a silent contagion, moving strictly bottom-up along the monetization funnel.
The first domino to fall is an unprecedented chill across consumer spending.
As generative AI displaces professionals across administrative support, translation, entry-level software engineering, graphic design, and paralegal consulting—or depresses compensation through widespread labor market oversupply—the core drivers of modern consumer economies will shift into aggressive defensive saving. Discretionary spending will be excised: vehicle purchases postponed indefinitely, travel plans scrapped, luxury merchandise gathering dust on showroom shelves, and subscription services aggressively canceled.
The second domino falls in tandem: enterprise clients enter a spiral of revenue erosion and severe cost containment.
Faced with an increasingly defensive consumer base, non-tech enterprises that invested heavily in AI infrastructure—firms like Ford, Disney, or Target—will confront an unforgiving financial reality: white-collar layoffs may have delivered meaningful operating-cost reductions, but aggregate revenue will contract far faster as demand dries up.
Faced with declining top-line revenues and tightening cash reserves, CFOs will abandon expansive transformation narratives in favor of austere financial discipline. Corporate software spend will face intense scrutiny. AI co-pilots billed at $30 per seat per month, once heralded as indispensable productivity multipliers, will be reclassified as unjustifiable balance-sheet luxuries unless they directly yield verifiable sales. Sweeping cancellations and strict licensing caps will follow.
As enterprise software procurement freezes, the shockwave hits the middle tier: cloud hyperscalers lose their growth momentum.
Leadership across Microsoft Azure, Google Cloud, and AWS will reckon with enterprise AI demand that falls dramatically short of internal forecasts. Parabolic cloud revenue trajectories will stall and tip into contraction. Crucially, the tens of billions of dollars in quarterly GPU depreciation remain fixed, immutable balance-sheet charges. Wall Street analysts will stop pricing in long-term AGI speculation, shifting instead toward hostile inquiries regarding return on invested capital (ROIC). Facing sharp valuation contractions, hyperscalers will be forced to drastically reduce or outright freeze future data center capital expenditures.
Finally, the seismic shock hits the top of the food chain, puncturing the compute narrative entirely.
When hyperscalers halt massive chip procurement, the party abruptly ends. Upstream hardware beneficiaries like Nvidia have had multi-trillion-dollar valuations pegged to the assumption of sustained, exponential hardware demand spanning a decade. In equity markets, missed growth is fatal. A deceleration in forward guidance triggers a brutal Davis Double Play: downward revisions in baseline earnings compounded by a severe compression in price-to-earnings multiples. The valuation bubble underpinning the entire AI compute sector will collapse under the inescapable gravity of vanishing aggregate demand.
Fisher’s Ghost: Debt-Deflation and the Stress on Fiat Structures
Had this dynamic been confined to a speculative correction in tech valuations, it would simply represent a routine repricing of financial assets. However, an AI-induced aggregate demand failure risks awakening the most destructive force in macroeconomics: debt-deflation.
In 1933, observing the root causes of the Great Depression, economist Irving Fisher formalized a structural trap: when an economy enters a deflationary regime characterized by falling prices and asset values, personal incomes drop in nominal terms, while fixed nominal liabilities—such as residential mortgages and auto loans—remain entirely unadjusted.
This creates an inescapable squeeze on the modern middle class.
The proliferation of advanced AI may very well drive the marginal cost of digital services, content generation, and informational diagnostics toward zero. Yet human beings remain carbon-based entities bound by physical constraints: we require real shelter, caloric intake, and base-load utility power. The contemporary middle class carries long-term mortgages denominated in conventional fiat currencies (USD, HKD, GBP) amortized over decades.
The resulting disconnect is uncompromising: an analytical professional whose role is automated cannot service a contractual monthly mortgage payment using free generative models. Financial institutions do not accept source code or algorithm access; they demand sovereign fiat.
To service invariant monthly debt obligations amid deteriorating earnings, displaced households are forced to liquidate assets—equities, property, and managed funds—at substantial discounts. When this liquidation occurs en masse, asset markets enter a disorderly stampede. As residential property values decline below outstanding loan principal, underwater mortgages surge, non-performing loans flood commercial banks, and private credit freezes. Unable to roll over working capital, commercial enterprises collapse, unleashing broader secondary unemployment.
This constitutes a deeply rational, devastating economic paradox: AI delivers an unprecedented abundance of digital productivity, yet because it fails to resolve the rigid nominal constraints of the physical debt system, that very productivity threatens to force the macroeconomy into a deflationary depression.
Conclusion: The Self-Consuming Ouroboros
Viewed in its entirety, this trillion-dollar capital allocation race mirrors the ancient archetype of the Ouroboros—the serpent locked in a compulsive cycle of devouring its own tail.
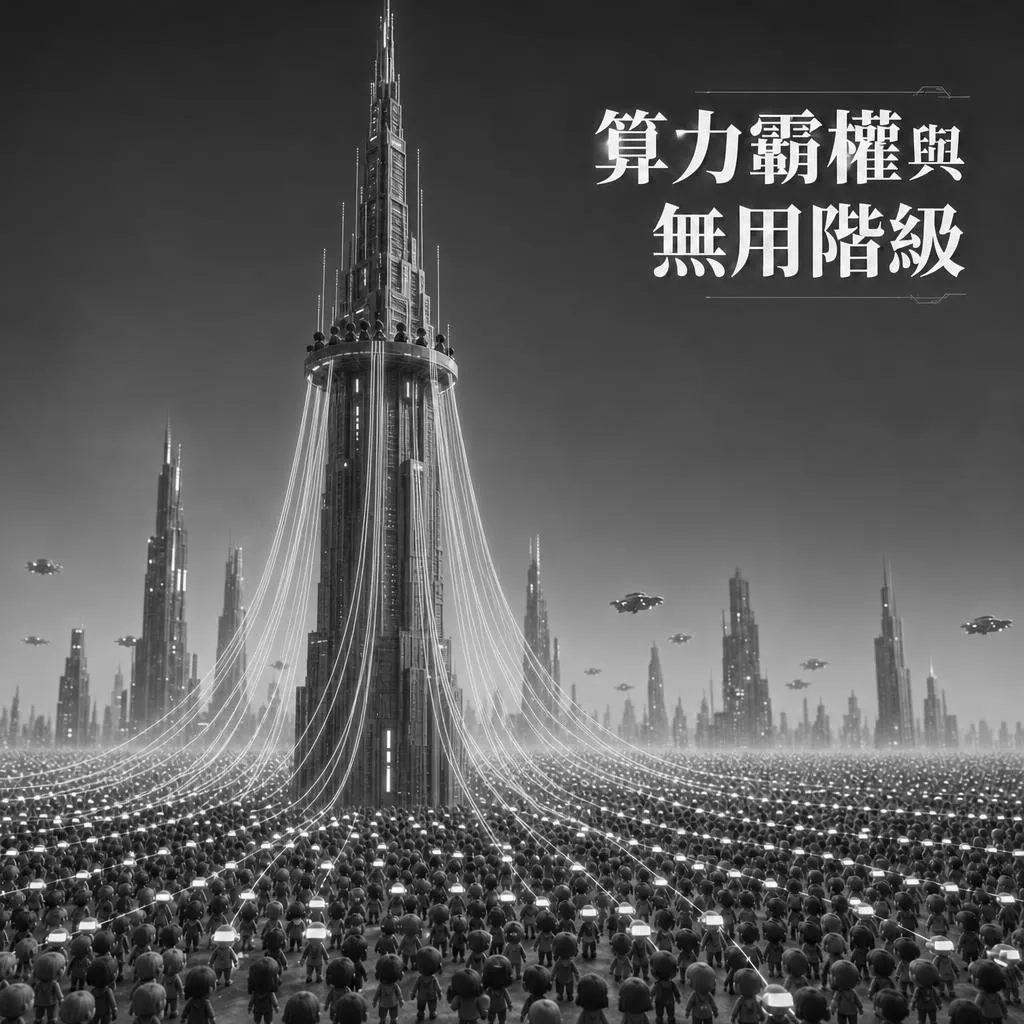
In relentless pursuit of operating efficiency and margin expansion, capital deployed unprecedented resources to automate cognitive labor. Yet in removing human labor from the production loop, it simultaneously dismantled the consumer foundation required for enterprise monetization. Tech monopolies sought to architect a self-sustaining loop powered by silicon and algorithms, independent of broad societal participation. Ultimately, they will find that stripped of the purchasing power of human labor, a compute empire is merely a golden tower built on shifting sand.
If existing macroeconomic frameworks cannot withstand the dislocation caused by this productivity shift, a systemic correction is not a tail-risk event—it is a temporal inevitability.
(End of Part One: The Fear of Capital and the Macroeconomic Gridlock)
Proceed to Part Two: Chapter 5: The Fractured Society and the Emergence of the “Superfluous Class”
All articles and images on this website are original works by the author and are copyrighted. Without permission, please do not arbitrarily reproduce, copy, or use for commercial purposes; if you wish to reproduce, please [contact this site] in advance to obtain authorization.
Disclaimer: The content of this article is for academic discussion, ideological exchange, and reference purposes only. The philosophical views mentioned herein do not represent the stance of this website or its authors, nor do they constitute any psychological, financial, or life coaching advice. Readers are solely responsible for their own choices and lifestyles. This website and its owners shall not be held liable for any direct or indirect consequences arising from reading this article.